SAP ME21N: How to Create an Asset Purchase Order – Step-by-Step
Purchase Order (PO) is a formal document issued by a buyer to a supplier, indicating the intent to purchase specific products or services at predefined terms and conditions. In SAP MM, the Purchase Order process is designed to ensure accurate ordering, efficient communication with suppliers, and seamless integration with other business processes. This guide walks you through creating an Asset Purchase Order specifically, covering account assignment category S, G/L account, and profit center. If you encounter any errors while following along, feel free to send a screenshot to pramod@learntosap.com, and I will help you resolve the issue.
✅ Asset Purchase Order in SAP – Create Asset PO Using ME21N
Purchase Order (PO) is a formal document issued by a buyer to a supplier, indicating the intent to purchase specific products or services at predefined terms and conditions. In SAP MM, the Purchase Order process is designed to ensure accurate ordering, efficient communication with suppliers, and seamless integration with other business processes.
An Asset Purchase Order sits at the intersection of SAP MM and SAP FI Asset Accounting, which is exactly why it deserves its own dedicated walkthrough separate from a Standard PO used for regular consumption items. Unlike a routine material purchase, whose cost typically hits the profit and loss statement as an immediate expense, an asset purchase is capitalized onto the balance sheet and depreciated over its useful life. This is precisely what account assignment category S (Capital Item) tells the system to do - route the cost to an asset master record rather than expense it outright.
Related Transaction Codes
| Transaction | Purpose |
|---|---|
| ME21N | Create Purchase Order (including Asset PO). |
| ME22N | Modify Purchase Order. |
| ME23N | Display Purchase Order. |
📋 Types Of Purchase Order (PO) – SAP FICO Asset Purchase Order Process
Asset PO
3) Asset Purchase Order (PO): Asset PO is used for procuring fixed assets or capital goods. These are items that the organization will use internally and are expected to have a longer useful life. Examples of fixed assets include machinery, equipment, vehicles, etc. Asset POs typically include details like the asset's description, quantity, value, and depreciation information.
Because the goods themselves - machinery, equipment, a vehicle - are still delivered and received in a fairly standard way, an Asset PO usually keeps item category blank (Standard) rather than requiring a special item category. What makes it distinct from a routine material purchase is purely the account assignment: category S tells the system this cost belongs on the balance sheet as a fixed asset, not the P&L as an expense.
🔧 Go To – ME21N Purchase Order Creation Path
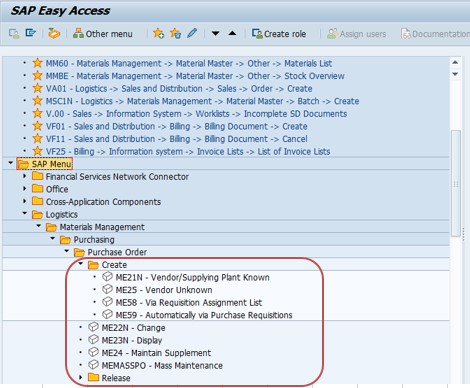
Go To: Logistics → Materials Management → Purchasing → Purchase Order → Create, or run transaction ME21N directly.
🔧 Follow Steps – Create an Asset Purchase Order
Go To Tcode ME21N. Run transaction ME21N to open the Purchase Order creation screen.
Select Standard PO. Choose the Standard PO document type, since the asset itself is still procured through a regular ordering process.
Select Vendor - 100369. Enter the vendor number supplying the capital asset.
Select Purchase Org - 1217, Purch Group - E01, Company Code - 1211. These organizational fields determine which purchasing unit owns the order and which company code the resulting asset capitalization will belong to.
Select (A) Account Ass Cat - S (Capital Item), then Select (I) Item Cat - Blank (Standard). Selecting account assignment category S tells the system this item is a capital asset, while item category blank keeps the line item processed as a standard deliverable good.
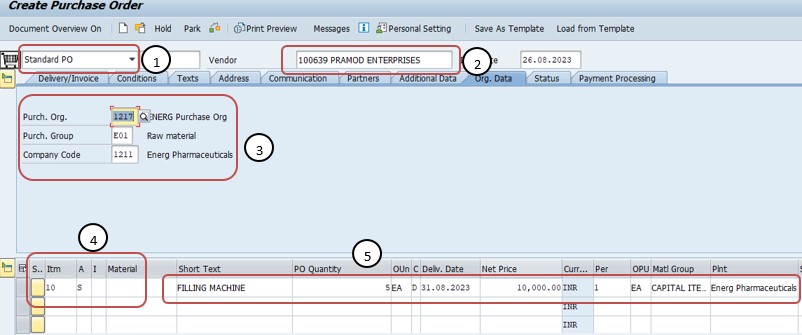
Enter Short Text, PO Qty, Delivery Date, Net Price, Material Group, Plant, etc. Fill in a clear description of the asset, the quantity being procured, the expected delivery date, negotiated net price, material group for reporting, and the receiving plant.
✅ Account Assignment Category
Account assignment category is used to determine how the costs incurred on a purchase order item will be assigned or distributed within the organization. In the context of an Asset Purchase Order, the relevant category is:
S (Capital Item): "Capital Item" indicates that the item being purchased is a capital asset, which typically means a long-term asset with a value above a certain threshold.
✅ Item Category
In SAP MM, the Item Category is a classification used to differentiate between different types of items being procured or managed within a purchase order. This helps the system understand how to process and manage the procurement of different types of items.
Blank (Standard Item): "Standard Item" generally refers to a standard type of material procurement where the item is procured for regular consumption or use - in this case, the physical delivery of the capital asset itself.
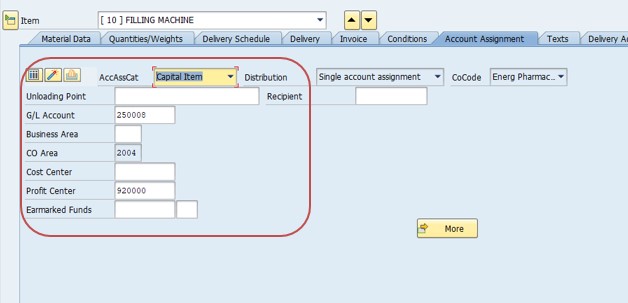
Enter G/L Account - 250008, Enter Profit Center - 92000. Completing the account assignment block with a specific G/L account and profit center is what finalizes where the asset's cost and eventual depreciation will be tracked.
✅ G/L Account (General Ledger Account)
G/L Accounts are used to record financial transactions in a company's general ledger. In the context of an Asset Purchase Order, G/L accounts are used to track and classify the financial postings related to the asset being procured. For example, the G/L account might represent an asset acquisition account related to the type of asset being purchased.
✅ Profit Center
The Profit Center in SAP represents a unit within a company that is responsible for generating revenues and incurring costs. It's used for internal reporting and analysis purposes. When creating an Asset Purchase Order, you might need to specify the profit center to associate the costs or benefits related to the asset with a particular profit center within your organization. This helps in tracking and analyzing profitability and cost distribution.
Then Check and Save PO. Running the Check function validates that account assignment category, G/L account, profit center, and all mandatory fields are complete and consistent before the Purchase Order is saved.
📋 Asset PO Key Fields at a Glance
| Field | What It Captures |
|---|---|
| Vendor | The supplier providing the fixed asset or capital good. |
| Purchasing Organization | The organizational unit responsible for negotiating and issuing the order. |
| Purchasing Group | The buyer or buying team assigned responsibility for the order. |
| Company Code | The legal entity whose balance sheet will carry the capitalized asset. |
| Account Assignment Category (S) | Indicates the cost is a capital item to be capitalized as a fixed asset rather than expensed. |
| Item Category (Blank) | Keeps the line item processed as a standard deliverable good. |
| G/L Account | The general ledger asset acquisition account that classifies the financial posting. |
| Profit Center | The internal unit associated with the asset's costs and benefits for reporting purposes. |
📋 Related SAP Transactions
| Transaction | Purpose |
|---|---|
| ME21N | Create a new Purchase Order, including an Asset PO. |
| ME22N | Change an existing Purchase Order. |
| ME23N | Display a Purchase Order without allowing changes. |
| AS01 | Create an Asset Master record, often maintained before or alongside the Asset PO. |
| AW01N | Display an Asset Explorer, showing the asset's value and depreciation over time. |
| F-90 | Post an asset acquisition directly in FI, relevant when reconciling capitalized costs. |
🎓 Interview-Style Questions and Answers
Q: What makes an Asset PO different from a Standard PO in SAP?
Both procure a physical, deliverable item and typically keep item category blank. The key difference is account assignment: an Asset PO uses category S (Capital Item), which capitalizes the cost onto an asset master record for depreciation, rather than posting it as an immediate expense.
Q: Why does an Asset PO still use item category blank instead of a special category?
Because the physical delivery and goods receipt process for the asset itself is standard - it's the account assignment category, not the item category, that tells the system to treat the cost as a capital acquisition.
Q: Why is a Profit Center required on an Asset PO?
The Profit Center identifies which internal unit is responsible for the asset's costs and benefits, supporting internal reporting and profitability analysis once the asset is capitalized and depreciated over its useful life.
Q: What happens if the G/L account or profit center is missing on an Asset PO?
The system will not allow the PO item to be saved, or will generate an account determination error, since Asset Accounting needs both the correct asset acquisition account and the responsible profit center to capitalize the asset correctly.
📚 Quick Glossary of Terms Used in This Guide
- Asset Purchase Order: A Purchase Order used to procure fixed assets or capital goods that will be capitalized and depreciated over time, rather than expensed immediately.
- Account Assignment Category: A classification, such as S for Capital Item, determining which cost object a PO item's expense is charged against.
- Capital Item: An item whose cost is capitalized as a fixed asset because it is a long-term asset with a value above a defined threshold.
- G/L Account: A general ledger account used to record and classify a financial transaction, such as an asset acquisition.
- Profit Center: An internal organizational unit used for tracking revenues and costs for reporting and profitability analysis.
- Asset Master Record: The record in SAP Asset Accounting that tracks an individual fixed asset's value, depreciation, and location.
📝 Governance for Asset Purchase Order Creation
Because an Asset PO's cost posts directly to a fixed asset and affects the balance sheet, most organizations maintain a documented governance process around which purchases qualify as capital items versus regular expenses, which G/L accounts and profit centers are appropriate for which asset classes, and who is authorized to approve capital spend above a given threshold. This is particularly important since capitalization decisions have tax and depreciation implications that extend well beyond the initial purchase.
Data quality governance matters here for the same reason it does for other PO types: an Asset PO created quickly, with an inconsistent or incorrect G/L account and profit center combination, tends to surface as a capitalization or depreciation problem later - once the asset has already been posted to the wrong asset class or profit center. Establishing a clear account assignment checklist for common asset categories keeps Asset PO quality consistent across a large buying organization over time.
💼 Real-World Scenario: Procuring New Production Machinery
Pooja Mishra, an SAP MM/FI consultant at Learn Pharmaceuticals, was asked to set up a Purchase Order for a new piece of production machinery after purchasing manager Rajesh Pawar confirmed vendor 100369 and the negotiated price. Since this was a capital asset rather than a routine consumable, Pooja used ME21N, selecting Standard PO document type and entering the vendor number.
She selected purchasing organization 1217, purchasing group E01, and company code 1211 to establish the organizational context, then selected account assignment category S (Capital Item) and kept item category blank (Standard), since the machinery would still be physically delivered and received in the usual way. Pooja entered a short text describing the machinery, the PO quantity, the expected delivery date, the negotiated net price, the relevant material group, and the receiving plant.
Finance analyst Priya Patil helped confirm the correct G/L account - 250008, an asset acquisition account for machinery - and profit center 92000, the production unit that would use and be responsible for the equipment. Once the account assignment was complete, Pooja ran the Check function to confirm there were no missing mandatory fields, then saved the Purchase Order. Upon delivery, the asset was capitalized against an asset master record, ready for depreciation tracking through Asset Explorer.
❗ Common Mistakes When Creating an Asset Purchase Order
- Using the wrong account assignment category - for example, K (Cost Center) instead of S (Capital Item) - which results in the cost being expensed instead of capitalized.
- Entering an inconsistent or incorrect G/L account and profit center pairing, causing account determination errors at goods receipt or invoice verification.
- Leaving the short text description too vague, making it difficult for approvers, auditors, or asset accounting to understand what asset was actually procured.
- Skipping the Check function before saving, only to discover missing mandatory account assignment fields once approval or capitalization begins.
- Not aligning the profit center with the department that will actually use and be responsible for the asset.
- Creating an Asset PO without first confirming an asset master record exists or is planned, causing delays at goods receipt.
✅ Best Practices for Asset Purchase Order Creation
- Confirm account assignment category S is selected correctly before entering item details, since it determines whether the cost is capitalized or expensed.
- Use a clear, specific short text description of the asset, rather than a generic label that won't be meaningful to asset accounting or auditors later.
- Verify the G/L account and profit center combination with finance before saving, especially for new or unusual asset classes.
- Coordinate with Asset Accounting to confirm an asset master record exists or will be created before goods receipt.
- Run the Check function before saving to catch missing mandatory account assignment fields early.
- Apply release strategy consistently for capital purchases, so spend above a defined threshold always receives appropriate management review.
📈 How Asset Purchase Order Data Powers Downstream Processes
An Asset PO's influence extends across the rest of the procurement and asset accounting cycle, which is exactly why getting the account assignment right at creation pays off well beyond the ME21N screen itself. The PO's G/L account and profit center determine exactly where the eventual asset acquisition will post and which unit's reporting reflects the new asset; its account assignment category S is what triggers capitalization rather than immediate expense recognition; and its short text description is often the primary record available to anyone later reviewing what the asset actually was.
Because capitalized assets are tracked and depreciated over multiple years, an inconsistency in the account assignment - a wrong profit center, a mismatched G/L account - is one of the more common root causes behind confusing account determination errors during goods receipt or invoice verification, rather than a problem with the invoice itself.
✅ Validating the New Asset Purchase Order Before Sending to the Vendor
Once an Asset PO is created and saved, it's worth running through a short validation checklist before it's sent to the vendor. Display the PO (ME23N) and confirm account assignment category S is set correctly along with the intended G/L account and profit center. Confirm the short text description clearly identifies the asset, and that quantity, delivery date, and net price all match what was actually negotiated. Confirm an asset master record exists or is planned to be created before the goods receipt is posted. Finally, confirm any release strategy has triggered correctly if the asset value exceeds a capital approval threshold.
Skipping this validation step is one of the more common reasons a newly created Asset PO causes confusion during goods receipt or invoice verification - usually an incorrect G/L account or profit center, or a missing asset master record to post the capitalization against.
📱 This Configuration in SAP S/4HANA
Transaction ME21N and the underlying Asset Purchase Order creation process work largely the same way in SAP S/4HANA as in classic ECC, since account assignment category S remains a core Materials Management and Asset Accounting concept. What has changed in S/4HANA is the availability of Fiori apps such as "Create Purchase Order" and "Asset Explorer," which offer a more modern, guided creation and asset value monitoring experience alongside the classic ME21N and AW01N transactions, along with improved integration between procurement and the new Asset Accounting (FI-AA) data model. Many S/4HANA implementations continue to rely on ME21N for Asset PO creation, particularly for complex account assignment scenarios, while Fiori-based apps are increasingly favored for day-to-day asset value tracking.
🎯 Conclusion
Creating an Asset Purchase Order in ME21N looks very similar to a Standard PO on the surface, but the account assignment - category S (Capital Item), the correct G/L account, and the appropriate profit center - is what actually determines whether the cost is capitalized as a fixed asset or expensed immediately. Selecting the correct vendor and organizational data, entering a clear asset description, and completing account assignment accurately are what separate an Asset PO that flows cleanly into Asset Accounting from one that generates capitalization or account determination errors downstream. Keep this guide handy the next time your organization needs to procure machinery, equipment, vehicles, or other capital goods through SAP.